The S&P 500 fell today for the seventh trading day in a row and closed in “correction territory.” That’s Wall Street’s term for a drop of 10% or more from a recent high, which for the index was October 6.
Markets are getting reacquainted with worry. The fragile state of markets, and the case for more sober investing, have been the subject of our memos for some time.
Being early is a way of being wrong, but it’s the way we preferred to be wrong. Heading to higher ground too early generally beats getting there too late. The decline has been swift, and it’s too soon to say whether this becomes a true bear market (a drop of 20% or more), or whether the tailwinds that carried stocks higher have given way to lasting headwinds.
Either way, a week like this can be unsettling. This update is meant to put things in perspective, especially for anyone who missed our earlier memos.
I’m grateful, as always, for our clients’ patience and trust. It lets me focus on markets, read, think, and act deliberately instead of reacting. That patience is one of the biggest advantages we have, and I don’t take it for granted. It doesn’t mean I don’t want to hear from you. Quite the opposite. If anything, big or small, is on your mind, please call. If you’ve held back out of politeness or a worry about being a bother, please don’t. That isn’t possible.
WHERE WE STAND
The top-heavy, technology-driven rally is now leading the market down. Our light holdings in that area held back our returns on the way up, perhaps too much. On the way down, they have limited our losses.
Two other things have helped:
- A lower stock allocation overall.
- A rotation within the market toward steadier businesses at less demanding prices. “Steadier” here means less tied to the economic cycle. This rotation has helped most of our largest holdings:
- our property and casualty insurance group (Chubb, Markel, White Mountains)
- Berkshire Hathaway, a conglomerate with a large insurance operation at its core
- Costco
- Allegion, which makes security doors and locks
- Ametek, a small conglomerate of leaders in niche electronic and electromechanical markets
Treasurys and high-quality corporate bonds helped this week. Bonds have been a drag overall, since most bond indexes are in the red for 2026 as interest rates have risen. As yields climbed, we have been adding gradually to two kinds of bonds:
- short- and intermediate-term bonds
- inflation-protected Treasurys (TIPS) maturing in about 10 years
I expect they’ll earn their keep if stocks keep sliding.
WHAT WE’RE BUYING
Because we came into this defensively, we can calmly start small positions in a few great companies that had been far too expensive.
Caterpillar is one. It was extremely overbought and overvalued at its June 30 high. After falling roughly half since then, the price looks far more reasonable. We are buying small starter positions now and will likely add if the stock falls further.
The shiniest companies, which I’ve cautioned against, have fallen hard, semiconductor makers included. Even Nvidia, the undisputed champion of the AI era, is down about 47% from its October 6 high. The scandal surrounding its founder, Jensen Huang, who resigned as CEO last week, made the drop worse.
Losing Huang is a real blow to Nvidia. But its rapid growth looks intact for at least the next couple of years. Its earnings kept rising while the stock fell, so it now trades at under 10 times forward earnings. We have been adding to our very small position as a result.
By almost any measure, we remain very light in technology. That’s especially true against the market itself: technology and internet companies, Tesla and Amazon still make up roughly half the value of the S&P 500.
WHAT I’M WATCHING
One concern I’ll write more about soon is a major shift in the supply of stock.
- Companies are issuing shares instead of buying them back. Heavy capital spending has caused this shift. Buybacks shrink the supply of shares and, all else equal, support prices. Issuance does the opposite.
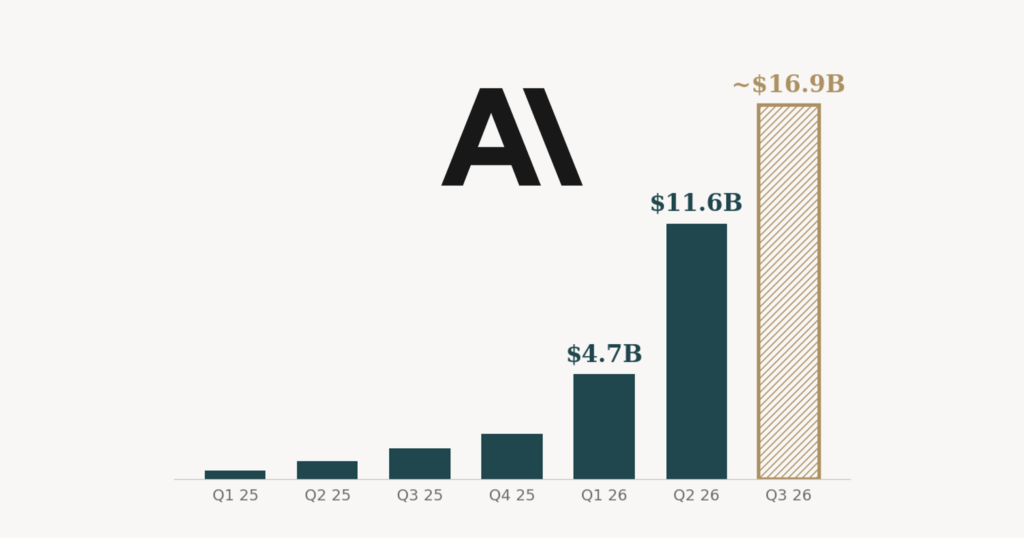
- Trillion-dollar IPOs are adding enormous new supply. SpaceX listed in June and Anthropic this week, with more likely to come.
In the past, surges in share issuance and IPOs have often preceded trouble.
We’ll be watching closely. In the meantime, please reach out with any question, however small. Our purpose is to serve and support you, always, and we welcome every chance to prove it.
This article is provided for informational and educational purposes only and does not constitute investment, legal, or tax advice. The views expressed are those of the author as of the date published and are subject to change without notice. References to specific securities are not recommendations to buy or sell any security, and Regency Capital Management and its clients may hold positions in the securities mentioned. Regency Capital Management, Inc.® is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Regency Capital Management and its representatives are properly licensed or exempt from licensure. Past performance is no guarantee of future returns. Investing involves risk and possible loss of principal capital. No strategy can ensure success or protect against loss.
About the Author
Neil Rose, CFA, is the founder and CEO of Regency Capital Management.